
Date: June 13, 2026
Ticker: META 0.00%↑
Market Cap: ~$1.44 Trillion
1. Company Overview
The Core Business & Revenue Model
Meta Platforms is the world’s dominant social networking and digital advertising conglomerate. It operates a vast “Family of Apps” ecosystem, generating nearly all of its revenue by serving targeted advertisements to its massive global user base. Recently, the company has aggressively pivoted into artificial intelligence, embedding proprietary AI infrastructure directly into its ad-targeting algorithms and consumer-facing applications.
Meta operates almost entirely on an ad-supported digital platform model. Advertisers bid for placement across its feeds, stories, and messaging interfaces, leveraging Meta’s unprecedented user data to maximize campaign conversion rates.
Main Products & Services
Family of Apps: The core social ecosystem comprising Facebook, Instagram, WhatsApp, and Threads.
Meta AI & Superintelligence: Advanced AI integration, featuring real-time business assistants, the newly introduced “Muse Spark” tools, and models actively developed by the Meta Superintelligence Labs.
Reality Labs: The division focused on augmented and virtual reality hardware, including the Quest headsets and Ray-Ban Meta smart glasses, serving as the foundation for the company’s long-term metaverse ambitions.
Management Team
Mark Zuckerberg (Founder & CEO): Retains absolute voting control over the company. He has recently refocused the company on aggressive AI integration, streamlining teams, and heavily investing in top-tier AI infrastructure.
Susan Li (CFO): Known for her disciplined approach during the “Year of Efficiency,” she is now navigating the financial messaging surrounding Meta’s massive up-cycle in data center and hardware capital expenditures.
2. Growth Prospects & Key Challenges
Future Growth Prospects
Digital Ad Dominance: Emarketer projects that Meta will surpass Alphabet in digital ad revenue in 2026, reaching $243.46 billion globally, fueled heavily by AI-powered ad automation tools and expanding ad loads on WhatsApp and Threads.
Surging Monetization Efficiency: Meta is extracting more value per user than ever before. In Q1 2026, the Family Average Revenue per Person (ARPP) climbed to $15.66, representing a massive 27% year-over-year increase.
Autonomous AI Agents: The company is actively building AI agents designed to perform work tasks autonomously, utilizing deep tracking software and internal AI models to reshape enterprise workflows.
Key Challenges & Risks
Massive Capital Expenditures: Meta recently raised its full-year 2026 capital expenditure guidance to an astonishing $125 billion to $145 billion. This reflects the immense cost of AI chips and infrastructure, creating short-term margin pressure and sparking investor volatility.
User Base Saturation: Family Daily Active People (DAP) reached 3.56 billion in Q1 2026. However, this represented a slight quarter-over-quarter decline, attributed to internet disruptions in Iran and WhatsApp restrictions in Russia. Finding net-new users is becoming mathematically difficult.
Regulatory Scrutiny: The company continuously battles global youth safety concerns, potential legislative actions, and antitrust scrutiny over its data collection practices.
3. Competition & Market Landscape
Key Competitors
Digital Advertising: Alphabet (Google Search, YouTube), Amazon Ads.
Social & Short-Form Video: TikTok (ByteDance), Snap, X.
AI Infrastructure & Models: OpenAI, Anthropic, Google (DeepMind).
Strategic Strengths & Weaknesses
Alphabet (Strength): Google captures high-intent search queries, making its ads highly valuable for immediate purchase conversions.
TikTok (Strength): Retains a powerful grip on younger demographics and organic viral content distribution.
Meta (Differentiator): Meta operates an unparalleled closed-loop ecosystem spanning 3.56 billion daily users. By integrating AI seamlessly into Facebook and Instagram feeds, Meta forces competitors to fight against an algorithm that hyper-optimizes user engagement and advertiser ROI simultaneously.
Market Share
Global Duopoly Leader: Meta operates alongside Alphabet in a functional digital advertising duopoly. Its ability to command an average price per ad increase of 12% year-over-year in Q1 2026 proves its pricing power remains entirely intact despite heavy competition.
4. Financial Analysis & Live Valuations
Valuations & Historical Snapshot (As of June 13, 2026)
Stock Price: ~$570.98
Market Cap: ~$1.44 Trillion
P/E Ratio (TTM): ~20.67x
Recent Earnings & Conference Call Notes (Q1 Fiscal 2026)
Top-Line Surge: Q1 2026 revenue soared to $56.31 billion, a 33% year-over-year increase, significantly beating analyst estimates.
Bottom-Line Profitability: Net income hit $26.77 billion. This was heavily inflated by an $8.03 billion one-time tax benefit. Excluding this benefit, diluted EPS would have been $7.31 (still a massive beat over the $6.65 forecast).
Operating Leverage: The company generated a phenomenal 41% operating margin, resulting in $22.87 billion in income from operations.
Cash Flow & Capital Returns: Despite massive infrastructure investments, Meta generated $12.39 billion in free cash flow and paid out $1.35 billion in dividends.
Financial Health Checklist
Revenue Growth: Outstanding. Expanding at 33% YoY at a $56B+ quarterly scale is incredibly rare.
Margins: Elite. A 41% operating margin highlights immense profitability.
Free Cash Flow: Highly resilient, capable of funding their massive AI ambitions internally without taking on restrictive debt.
Red Flags: The core business is flawless, but the primary red flag is the explosive $125B–$145B Capex budget. If the AI tools fail to drive corresponding ad revenue growth, return on invested capital will plummet.
5. Live Data & 5-Year Projections Context (2026–2030)
Meta’s future relies heavily on whether their massive data center infrastructure build-out will yield a direct monetization pipeline or simply serve as the baseline cost to compete in the new AI era.
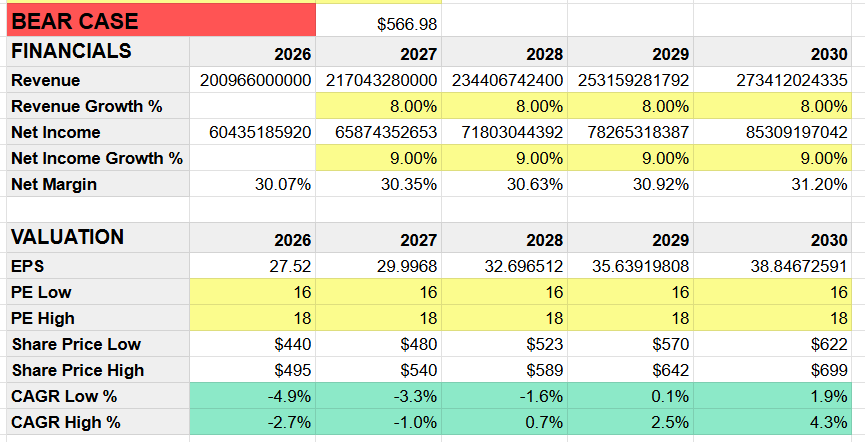
Bear Case:
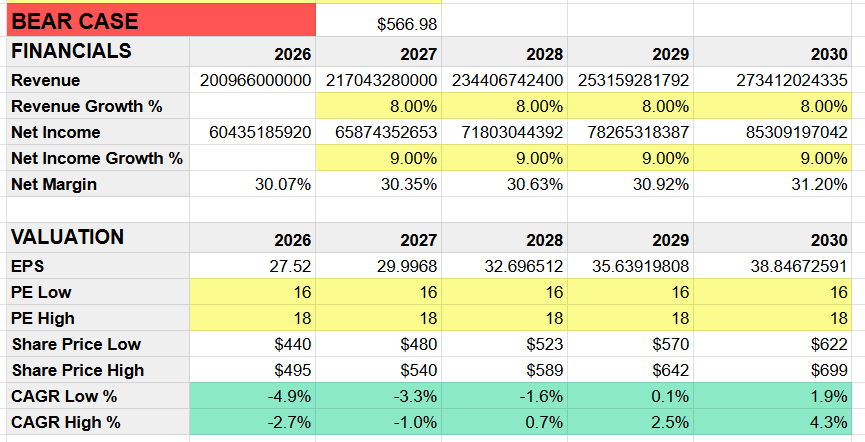
In this scenario META 0.00%↑ delivers a CAGR between +1.9% and 4.3% .
TikTok re-accelerates, and younger users abandon Facebook/Instagram. The $130B+ AI infrastructure spend fails to produce a consumer application that justifies the cost. Operating margins compress as depreciation costs catch up.
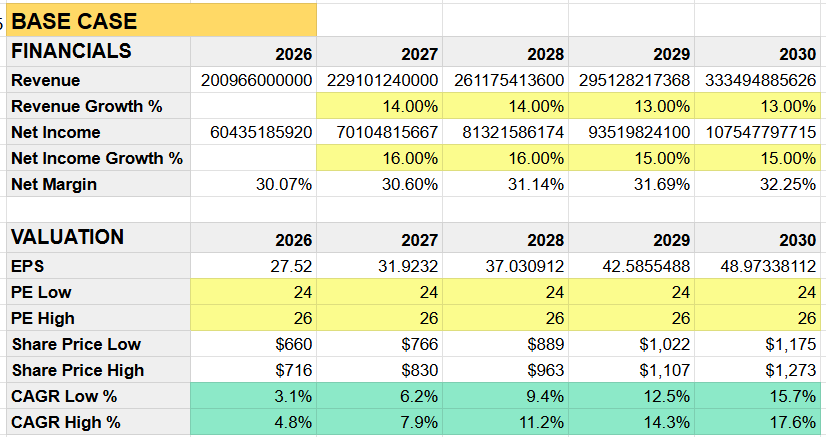
Base Case:
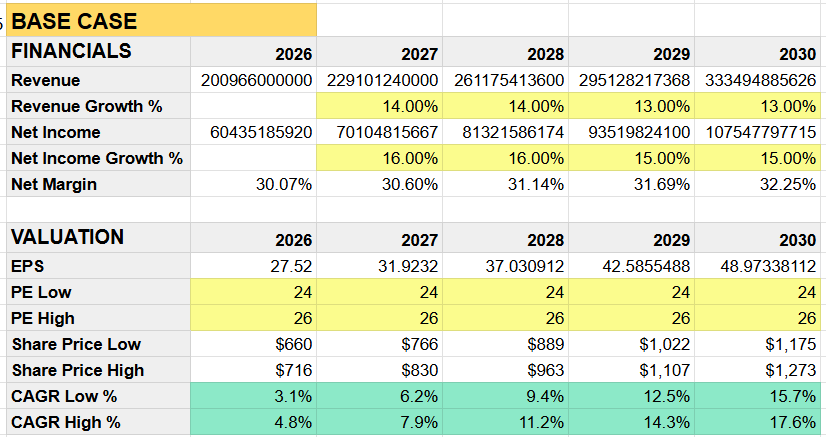
In this scenario META 0.00%↑ delivers a CAGR between +15.7% and 17.6% .
Meta seamlessly integrates open-source AI models into enterprise ad managers. They officially eclipse Alphabet in ad share as projected, sustaining strong double-digit growth. WhatsApp successfully transitions into a massive global commercial hub.
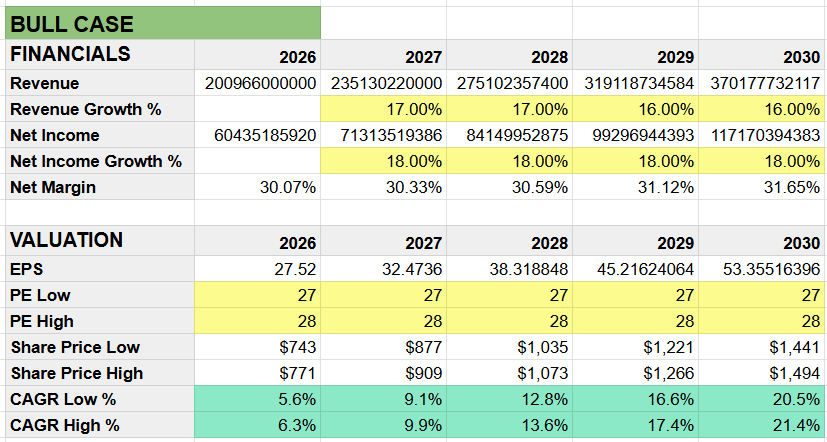
Bull Case:
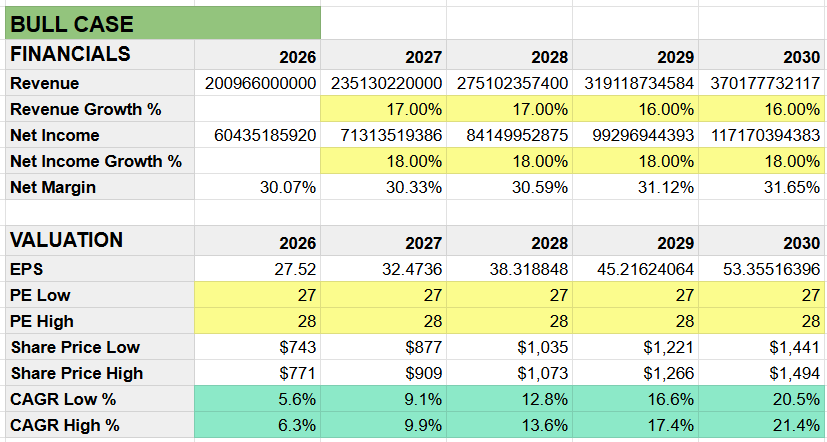
In this scenario META 0.00%↑ delivers a CAGR between +20.5% and 21.4% .
Meta’s autonomous AI business assistants revolutionize enterprise customer service and e-commerce. Reality Labs finally finds mainstream adoption with next-generation smart glasses, creating a closed-loop hardware/software ecosystem that permanently cements a multi-trillion dollar valuation.
6. Conclusions
Wall Street experienced a brief moment of sticker shock over Meta’s raised $125B–$145B capital expenditure guidance. However, the underlying fundamentals suggest this spending is fully justified. Generating $56.3 billion in quarterly revenue with a 33% growth rate and a 41% operating margin proves Meta’s core ad engine is performing flawlessly. With ARPP jumping 27% YoY and Emarketer projecting they will overtake Alphabet in global digital ads this year, Meta is demonstrating that it can successfully self-fund the largest technological pivot in corporate history while remaining remarkably profitable
Base case is very likely